What is the market size and industrial significance of the Hospital Command Center Operations Market?
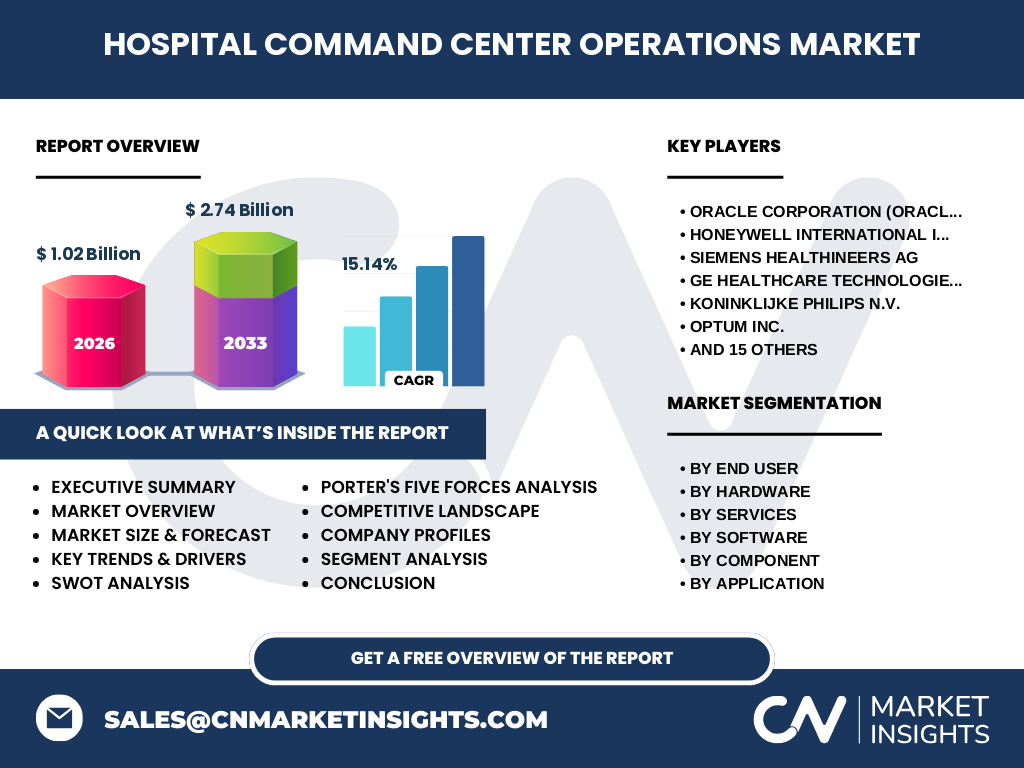
Our analysis indicates that the Hospital Command Center Operations Market achieved a valuation of $1.02 Billion in 2026, laying the groundwork for widespread adoption of centralized healthcare logistics. These mission-control environments integrate disparate EHRs, IoT asset tags, and nurse call systems to optimize acute care delivery. Regulatory pressures from agencies like CMS regarding wait times and readmission penalties make these operational hubs essential for modern health systems.
Structural Growth Drivers and Market Restraints
The market is propelled by a 15.14% CAGR driven by chronic bed shortages, aging populations, and rising inpatient acuity. Conversely, the Hospital Command Center Operations Market industry trends reveal significant restraints, notably prohibitive upfront capital expenditures for on-premise infrastructure and complex interoperability hurdles. Health systems struggle to harmonize legacy electronic health records with real-time locating systems, creating integration bottlenecks.
Emerging Technologies and Shifting Paradigms
The shift toward predictive analytics and cloud architecture is transforming the Hospital Command Center Operations Market. Institutions are rapidly abandoning rigid on-premise setups in favor of Cloud-Based Virtual Command Centers. This transition leverages advanced machine learning models for early discharge planning and real-time nurse-to-patient ratio optimization, directly mitigating clinician burnout while accelerating patient throughput across emergency departments.
How did the COVID-19 pandemic reshape the Hospital Command Center Operations Market?
The pandemic served as an unprecedented stress test, permanently altering the Hospital Command Center Operations Market analysis. Surging ICU admissions forced hospitals to adopt centralized visibility tools to track mechanical ventilators, negative pressure rooms, and personal protective equipment in real time. This crisis management utility accelerated post-pandemic recovery trajectories, converting command centers from discretionary nice-to-haves into permanent clinical triage lifelines.
Competitive Landscape and Strategic Market Concentration
The Hospital Command Center Operations Market features a highly consolidated competitive matrix dominated by health IT giants and specialized logistics innovators. Industry stalwarts like GE HealthCare Technologies Inc. and Koninklijke Philips N.V. leverage expansive hospital networks to deploy proprietary wall-board visualization systems. Meanwhile, agile software specialists like LeanTaaS Inc. and Qventus Inc. carve out niches through AI-driven operating room scheduling and capacity orchestration.
Executive Summary: Key Findings in the Hospital Command Center Operations Market
Our comprehensive evaluation projects the Hospital Command Center Operations Market to surge from $1.02 Billion in 2026 to $2.74 Billion by 2033. This hyper-growth is anchored by a robust 15.14% CAGR. Success in this ecosystem requires a dual focus: robust clinical workflow software deployment and flexible deployment models that accommodate both sprawling academic medical centers and resource-constrained community hospitals.
Market Forecast and Valuation Trajectory (2027 to 2033)
The Hospital Command Center Operations Market market size is poised for exponential expansion, scaling from its 2026 baseline to reach $2.74 Billion by the conclusion of 2033. Maintaining a stellar 15.14% CAGR, growth will be heavily concentrated in specialized services and predictive software segments. As value-based care mandates expand, hospitals will increasingly allocate capital toward automated capacity management and clinical decision support tools.
Segmentation Analysis Across Hardware, Software, Services, and End-Users
The Hospital Command Center Operations Market is segmented by Component, Software, Hardware, Services, End User, Application, Hospital Type, and Deployment Model. Clinical Workflow Management Software and Patient Flow Management Software dominate software demand. The End User landscape spans Hospitals, Healthcare Systems, Specialty Clinics, and Ambulatory Care Centers, with large integrated delivery networks driving bulk procurement of servers, networking equipment, and display walls.
Geographic Distribution and Regional Performance Dynamics
Regional performance within the Hospital Command Center Operations Market reflects stark disparities in healthcare IT infrastructure spending. North America maintains absolute market dominance, propelled by stringent hospital readmission reduction programs and high electronic health record adoption. Meanwhile, Asia-Pacific emerges as the fastest-growing regional frontier, driven by aggressive government investments in smart hospital initiatives across metropolitan hubs in Southeast Asia and East Asia.
In-Depth Regional Review of Healthcare Logistics Infrastructure
Evaluating localized market constraints reveals that North American hospitals prioritize advanced Staffing And Workforce Optimization to counter nursing shortages. In contrast, European health systems focus heavily on Emergency And Crisis Management integration to comply with strict public healthcare directives. Regional reimbursement frameworks directly dictate whether facilities invest in On Premise Command Center hardware or scalable Cloud-Based Virtual Command Centers.
Company Profiles and Strategic Positioning
Industry leaders occupy distinct strategic domains within the Hospital Command Center Operations Market. Oracle Corporation (Oracle Health) and Epic Systems Corporation embed command center analytics directly into core electronic health record platforms. Concurrently, specialized innovators like TeleTracking Technologies Inc. and ABOUT Healthcare dominate patient transfer logistics, while hardware providers like Honeywell International Inc. secure deployments through advanced Workstations And Computing Devices.
Porter's Five Forces Analysis of the Command Center Ecosystem
The Hospital Command Center Operations Market exhibits moderate-to-high competitive rivalry, tempered by significant switching costs once a hospital commits to a specific software vendor. Bargaining power of buyers is substantial due to large enterprise contract sizes, while threat of new entrants remains constrained by stringent data security compliance requirements, such as HIPAA and GDPR, alongside complex clinical workflow integration hurdles.
SWOT Analysis of the Hospital Command Center Operations Market
Strengths include dramatic improvements in bed turnover rates and enhanced clinical decision support. Weaknesses involve high implementation friction and steep training overhead. Opportunities lie in expanding into Ambulatory Care Centers and deploying predictive AI algorithms. Threats encompass cybersecurity vulnerabilities targeting centralized patient data streams and potential resistance from clinical staff fatigued by alert noise.
Value Chain Analysis from Raw Materials to End-Users
The value chain of the Hospital Command Center Operations Market flows from semiconductor and server hardware manufacturers through enterprise software developers to ultimate deployment in Large Acute Care Academic Medical Centers and Community Hospitals. Value addition is heavily concentrated in the proprietary algorithms of Predictive Analytics Software and managed integration services that harmonize real-time data feeds into actionable clinician dashboards.
Strategic Investment Insights and High-Potential Areas
Investors eyeing the Hospital Command Center Operations Market should prioritize portfolio companies specializing in Managed Services and Cloud-Based Virtual Command Centers. As smaller community and rural hospitals seek centralized efficiencies without massive capital expenditures, subscription-based SaaS delivery models offering modular capacity and patient flow management software represent the highest-yield investment vectors.
Conclusion and Strategic Key Takeaways
The trajectory of the Hospital Command Center Operations Market underscores a permanent evolution toward data-driven acute care oversight. Surging from $1.02 Billion in 2026 to $2.74 Billion by 2033 at a 15.14% CAGR, the market rewards vendors capable of seamless EHR integration and advanced AI-driven workflow optimization. Health systems failing to adopt these operational hubs risk severe capacity bottlenecks and financial penalties under value-based care models.
Research Methodology and Baseline Triangulation
Our market sizing for the Hospital Command Center Operations Market relies on rigorous triangulation. We synthesize primary stakeholder interviews with chief medical officers, chief nursing informatics officers, and IT directors, cross-referenced with secondary macroeconomic indicators, regulatory filings from named industry participants, and proprietary trade registry data. Bottom-up hardware shipment data is reconciled with top-down healthcare IT budget allocations to establish authoritative baseline estimates.
Scope of the Report and Coverage Parameters
This research report evaluates the global Hospital Command Center Operations Market across all defined software, hardware, services, deployment models, and end-user segments. Limitations include the exclusion of ambulatory settings lacking formal digital infrastructure and localized regulatory variances outside North America, Europe, and Asia-Pacific. All financial projections are denominated in US dollars and account for prevailing macroeconomic headwinds through the forecast horizon.
Recent Industry Developments and Strategic Market Moves
Recent strategic maneuvers in the Hospital Command Center Operations Market highlight an acceleration of M&A activity and cross-sector partnerships. Major tech conglomerates are partnering with specialized analytics providers to bundle AI modules into existing health system frameworks. Recent product launches emphasize interoperable cloud suites designed for Critical Access And Rural Hospitals, democratizing access to advanced patient flow and capacity management tools previously restricted to elite academic centers.